Reading Time: 6 minutes

Purpose-driven financial planning: Create a plan with your values in mind

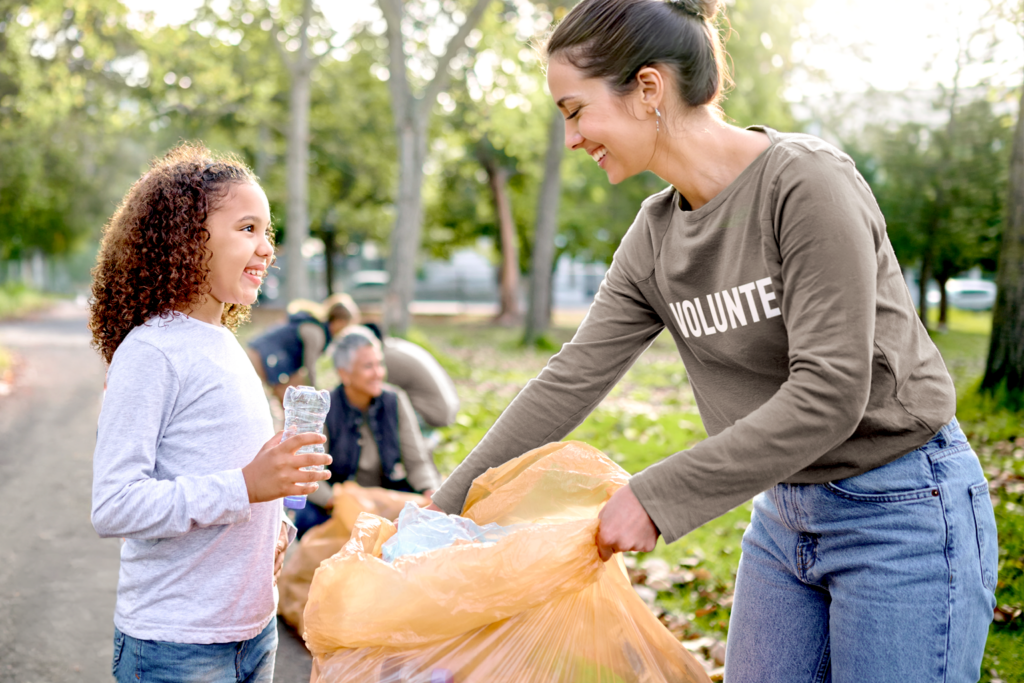
Woman and child volunteering to pick up litter

Financial goals are more meaningful when they’re connected to your “Why.” Purpose-driven financial planning starts with identifying your core values and then using them to guide how you save, spend, invest, give, and prepare for retirement.

Key Takeaways

How does values-based financial planning work?

Financial planning naturally involves numbers. How much will you need for retirement? When do you want to retire? How much are your investments earning?

But the numbers are only part of the story.

What's your WHY behind hitting these numbers?

Maybe you’re building financial security so you are less concerned about market fluctuations. Perhaps you want the freedom to retire on your terms, spend more time with family, travel, support a cause, or help the next generation.

Values-based financial planning starts with those priorities and uses them to help guide financial decisions.

Interest in values-based approaches has been particularly notable among women and younger generations, but the concept isn’t limited to any particular group.

Anyone can choose to put more purpose behind their broader financial decisions and their portfolio.

How can you identify your core values?

Values are the deep priorities that help explain why certain goals matter to you. They may include things such as family, independence, security, generosity, freedom, community, faith, experiences, well-being, achievement, equality, simplicity, or legacy.

To uncover yours, consider:

Try identifying three to five values that stand out. Then use them as a filter when making financial decisions.

How can values shape your financial goals?

The next step is translating something abstract into a tangible goal.

If family matters deeply, saving might mean helping fund a child’s education, caring for an aging parent, or creating opportunities to spend more time together.
If freedom is important, financial independence may represent the ability to retire sooner, change careers, or simply have more control over your time.
If generosity is a priority, charitable giving can become an intentional part of your financial plan rather than something you consider only after every other goal has been met.

And if you value security or peace of mind, you may place greater importance on creating reliable retirement income that isn’t dependent on market performance.

That process can also change how you think about individual financial products. An annuity, for example, may represent more than a source of guaranteed lifetime income. For someone who values security, independence, or the freedom to enjoy retirement with less concern about market volatility, that income can help support a deeply personal priority.

Do you have to choose between portfolio performance and your personal values?

One way to think about values-based planning is “voting with your dollars” while continuing to pursue your own financial objectives.

That might mean being more intentional about the companies you support, the investments you select, or the causes you give to. But it doesn’t necessarily require choosing personal principles instead of performance.

The goal is to make thoughtful financial choices with a clearer understanding of why you’re making them.

How can a financial professional help?

Your financial professional doesn’t need to have the same values. What matters is whether they understand your priorities well enough to incorporate them into your financial plan.
Once you have determined the values that will drive your decisions, ask yourself:
Does my financial professional understand what I ultimately want to accomplish with my money?
You can also consider the reputation, priorities, and business practices of the financial companies you work with and whether those relationships are consistent with your values.

How can your financial values become part of your legacy?

What you pass down may eventually include more than financial assets. Families also pass along stories, perspectives, and beliefs about what money means and how it should be used.

A Legacy Charter can help bring those priorities to life for future generations. This personal document captures the values, experiences, intentions, and financial lessons you want to pass along. It might explain why giving back was important to you, why you prioritized financial security, or why creating meaningful experiences with family mattered just as much as leaving an inheritance.

Unlike a will or trust, which generally outlines how assets are to be managed or distributed, a Legacy Charter helps communicate the meaning behind your financial choices and the values you hope carry forward.

Can values change over time?

Your core values may remain fairly consistent, while the way they influence your finances may change dramatically over time.

Family might mean saving for education at one stage of life and helping adult children or planning a legacy at another. A career change, retirement, marriage, divorce, inheritance, or other life event can also shift your priorities.

Rather than starting your financial plan over, revisit it periodically with your financial professional and consider whether your current decisions still reflect what is most important to you.

Because the purpose of a financial plan isn’t simply to accumulate more.

It’s to help ensure the money you save, invest, and eventually use supports the life you envision.

If financial security is high on your list of values, one next step may be considering how much reliable income you’ll have available to cover essential expenses in retirement.

Building an income floor using sources such as Social Security, pensions, and annuities may help create that foundation.

ULPUB-019


Related Posts